On this page
A growth-stage manufacturer we brought live recently now runs like this. On the 2nd of each month, the first thing the owner does is open the reports: how much the business made last month, how much cash is left, which product line is losing money, which receivables need chasing. One page, the whole picture. For him, the close is the first two days of the month, and then it is done.
Most companies look different. When month-end arrives, the finance team goes into a sprint. By the time the books are closed and the reports reach the owner, it is usually mid-month. What the owner sees is always a set of books that is two weeks old.
Two pieces of survey data set the scene:
Ledge, 2025 Month-End Close Benchmark Report: about 18% of organizations close their books within 3 days.
APQC Open Standards Benchmarking: world-class finance teams close a month in 4.8 days on average, while laggards take more than 10.
Put the gap on a chart and it gets concrete. For the same monthly close, the difference between companies is roughly two weeks of operating visibility:
How fast finance teams close, worldwide
| Close performance | Days to complete |
|---|---|
| Top 25% | 4.8 days |
| Median | 6.4 days |
| Bottom 25% | ≥10 days |
Why is the gap this wide? That is what this article is about.
Management Purpose of the Monthly Close
Many people read the close as settling last month's books and preparing data for the tax authority. That framing is off. The close is closer to a monthly health check the owner runs on the business: did we make money this month, where did we make it and where did we lose it, are cash and inventory healthy. Run the check and it becomes clear. Its first job is to support business decisions. Filing taxes comes second.
How well you run that check makes a large difference:
Close quality and the owner's position
| State of the close | Where it leaves the owner |
|---|---|
| Not accurate | Decisions based on incomplete or inconsistent data |
| Accurate but slow | Finds the problem two weeks too late |
| Fast and accurate | Has the full operating picture at the start of the month, and can adjust within the same month |
The close is not only a question of speed. It is also a question of whether the numbers can be trusted. From the owner's seat, the requirements usually come down to three points:
- Accuracy: are the batch costs and unit gross margins you see actually right?
- Integrity: if someone adjusts the reports after the fact, can the historical numbers still be trusted?
- Consistency: sales says it booked 5 million this month, finance only recognizes 3 million. Where did the other 2 million go?
Business and Finance Responsibilities
Faced with the month-end sprint, companies usually reach for one of two fixes: work overtime, or replace the system. Overtime just throws more labor at the problem. Replacing the system, if operations and finance are still two separate ledgers, if no one owns the process, if posted documents can still be edited freely, leaves the problem where it was.
Neither action addresses the source of the delay. Close-cycle and data-quality issues usually occur in the following areas:
Five places the close gets stuck
| Management problem | What it looks like | Root cause |
|---|---|---|
| Source documents not fully posted | Goods receipts and deliveries get back-entered at month-end | Documents do not post to the system when the transaction happens |
| Inventory valuation unclear | This month's actual cost can only be estimated | Material, labor and overhead are not rolled into inventory cost automatically |
| Subsidiary ledgers do not reconcile | AR, AP and bank do not tie out | Incoming and outgoing payments are not reconciled against invoices line by line |
| Inventory does not tie | The system stock differs from the physical count | Goods receipts and issues are posted late, shrinkage is not recorded |
| Cross-department friction | No one decides whose cost it is or whether goods were received | No common posting rules, everything runs on manual coordination |
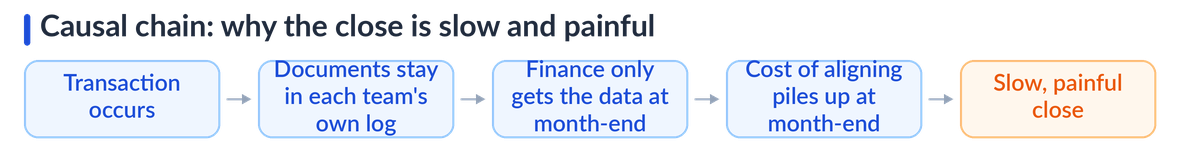
These five look different on the surface. Dig down and they share one cause: when the transaction happens, the data does not post to the same system. Operations and finance each keep their own ledger, then sit down at month-end to reconcile. What finance gets is only the result. It never sees the process.
The cause is usually straightforward. Source documents remain in departmental records when transactions occur, so finance receives the data only at month end. Reconciliation and adjustment work is therefore concentrated in the final days of the period instead of being processed throughout the month.
Main Close Controls
Since the root is the two separate ledgers, the priority is to bring operational and financial data into one ledger: post the source document when the transaction happens and generate the journal entry with it. This addresses three related problems together: missing document postings, unclear inventory valuation and book-to-physical inventory differences.
For the other two, the moves are these, plus one efficiency principle:
- Hand reconciliation to the system: bank statements and cross-system transactions match automatically, so no one ties out open items line by line.
- Settle ownership with rules: whose cost each item is, who confirms each goods receipt. Set the posting rules, assign them to a person, and the friction goes away.
- Spend time where it matters: grade customers and suppliers by credit limit, reconcile the important ones every month, and stretch the cycle for the minor ones. That saves finance real effort.
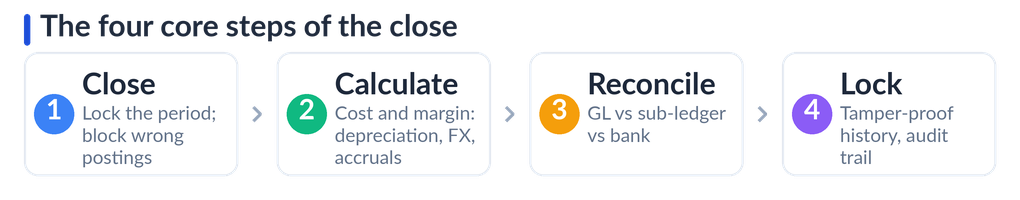
As a set of actions, one close comes down to four steps. Close the posting period so documents cannot post into the wrong month. Calculate so cost and margin come out right: the period-end costing run, the depreciation run, foreign-currency revaluation, and accruals. Reconcile the ledger against reality: general ledger against the subsidiary ledgers against the bank statement. Lock the posting period so history cannot be altered and every change leaves an audit trail.
How the system carries out each of these four steps is something the next article, What a good system does for you at close, takes apart.
Whether you do this or not shows up in a few close metrics:
Close metrics, before and after the process is sorted out
| Metric | Process not sorted | After it is sorted |
|---|---|---|
| Days to close | 10 to 15 days | 2 to 3 days |
| Reconciliation differences | Surface all at once at month-end | Surface in real time, cleared the same day |
| Report timeliness | Monthly numbers arrive mid-month | Full picture on day one |
| Report accuracy | Many manual adjustments, versions change often | Numbers fix at posting, stable and auditable |
An integrated finance-and-operations system makes it possible to keep the general ledger accurate day to day, so that month-end is only locking the posting period and producing statements. But whether the process flows, and whether responsibilities are assigned to named people, still comes down to design and control. That second part is what MTC has spent these years helping companies with: sort out the process, post the data into one ledger, break the close tasks down to specific roles, and stay with the company through the run-in period, rather than dropping off a system and leaving.
Management Use of Close Results
Once the close is sorted, what the owner opens on the first day of the month is a one-page operating dashboard:
What the owner can see: the operating dashboard
| What you look at | What it tells you | Decisions you can make without waiting for the close |
|---|---|---|
| Revenue, cost, gross margin | Whether you made money this month and where | Margin slipped: adjust purchasing or pricing this month |
| Cash flow, DSO and DIO | Whether cash is enough and turning fast | Tight: arrange ahead instead of finding out at month-end |
| Operating health | Whether the business flow is smooth | Data consolidated in real time, queryable the same day |
| Inventory health | How much has turned into obsolete stock | Book-to-physical gaps visible in real time, clear the slow movers |
| Receivables risk | AR aging: who owes and how overdue | Tighten credit limits, hold shipments |
In practice, once these are solved, much of the data no longer waits for the close at all. The feedback loop on the business compresses from forty or fifty days to three to five. Problems become visible within the month, and can be adjusted within the month.
The value of the close is not speed for its own sake. It is letting the owner see the situation earlier and decide earlier.
Year-End Close and Annual Operating Data
Many people treat the year-end close as a thirteenth month-end. The two answer different questions. The month-end answers how last month went. The year-end has to answer whether this year's direction is right and where the business goes next year. For the owner it is closer to a decision map for the coming year than a bill.
It is also the once-a-year settlement of stewardship: giving the board, shareholders, banks and the tax authority a true account of the year's results. It is the foundation for profit distribution and financing audits. On top of that it carries several year-only closing actions the month-end does not touch:
Year-only closing actions
| Action | What it does | Cost of doing it badly |
|---|---|---|
| Closing the year's P&L | Close income and expense accounts and roll the result into retained earnings | Get it wrong and next year's opening balances are wrong too |
| Impairment provisions | Assess slow-moving stock, bad debt and devalued assets item by item | The first place auditors look |
| Annual CIT settlement | Reconcile book profit to taxable income under the tax rules | Underpay when you should pay, miss a refund when one is due |
| Budget and performance baselines | Set next year's KPIs off the actuals | If the actuals are off, the KPIs are wrong at the root |
If you have multiple entities or foreign-currency operations, you also have to eliminate intercompany transactions cleanly and consolidate on a group basis.
So the next time month-end is about to put finance into overtime, or the urge to change the system comes back, it is worth stopping to ask:
Are we really short of people or short of a system, or is the data just not in one ledger yet, with the process, authority and accountability not yet assigned?
The next article turns to the tool: a system that connects operations and finance (in our implementations, usually SAP Business One), and what it can actually do for you at each of the four steps, close, calculate, reconcile, lock.
MTC Information. Deep focus on SAP Business One, making financial data truly serve the business.